The Numbers Behind the Slowdown
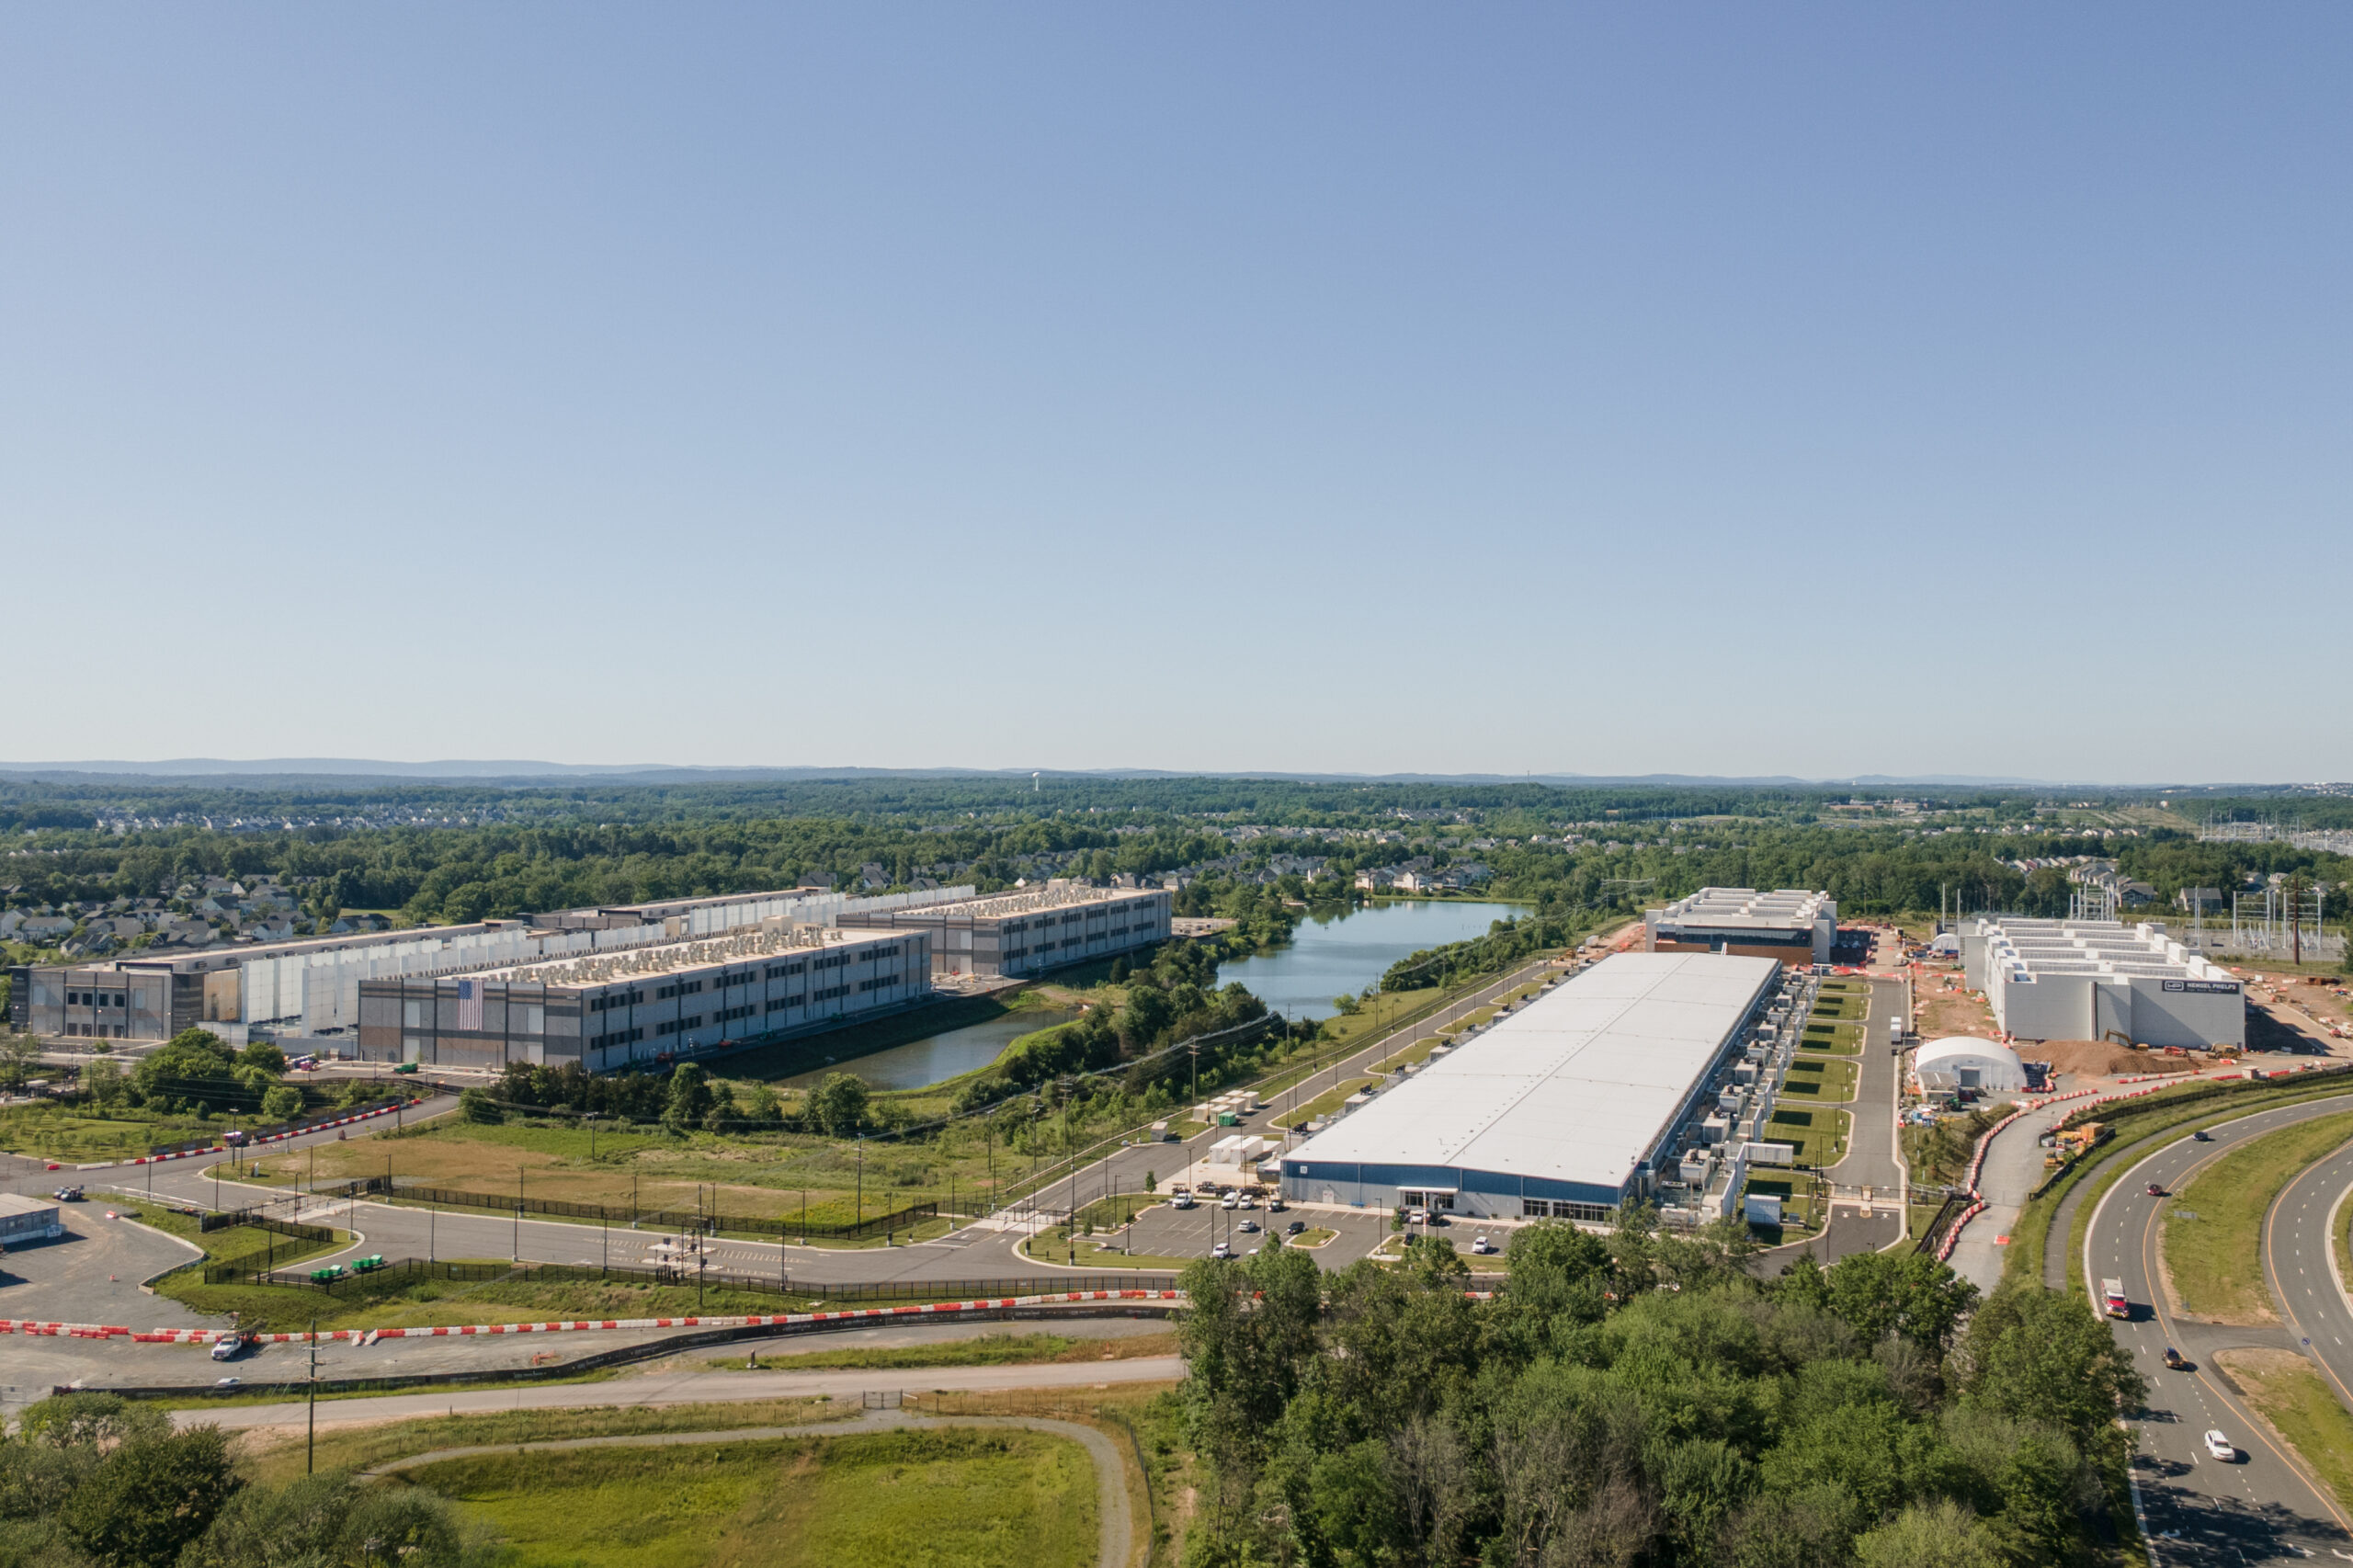
Data Center Watch, the tracking arm of AI intelligence firm 10a Labs, published its second quarter 2026 count of data center projects facing organized local opposition, and the numbers describe a buildout that keeps hitting friction even as the industry insists demand is insatiable. Forty five projects worth a combined 68 billion dollars were blocked or delayed by community pushback between April and June, a decline from the 75 cases worth roughly 130 billion dollars the group counted in the first quarter, but still a meaningful chunk of the capacity hyperscalers and enterprises are counting on for 2027 and 2028 workloads. The quarter over quarter drop is not obviously good news either, since it may simply reflect operators quietly relocating contested projects rather than opposition losing momentum.
Lead analyst Miquel Vila summarized the trend directly: "New groups continue to emerge, opposition is appearing across a wide range of states and jurisdictions, and online petition signatures continue to grow." The group now tracks more than 843 opposition organizations spread across 49 states, with only Hawaii absent from the list, and one Tennessee project drew more than 500,000 signatures on a single Change.org petition. That kind of grassroots scale, reached in a single county fight over a single facility, is the sort of number that gets a state legislator's attention regardless of how much tax revenue a developer is promising in return.
Where the Pushback Concentrates
The complaints driving these campaigns are consistent across regions: water consumption for cooling, strain on local electricity rates, noise from generators and cooling equipment, and skepticism that promised jobs and tax revenue justify the resource draw. These are not fringe concerns confined to a handful of activist groups; they are showing up in state legislative sessions, in gubernatorial directives like the one Texas issued this month, and in utility rate cases where residential customers are asking why their bills are rising alongside a nearby hyperscale campus. Utility commissions in several states have started requiring separate rate classes for large loads specifically because residential ratepayers organized around exactly this complaint and made it politically costly to ignore.
What makes this quarter's data notable is the geographic spread. Opposition is no longer concentrated in the handful of states that got the earliest and largest AI driven buildouts. It has become a near universal feature of the siting process, which means enterprises can no longer assume that moving a project to a friendlier state meaningfully reduces the odds of delay. A developer's pitch that a given county has never seen organized opposition is now closer to a description of the past than a prediction about what happens once ground actually breaks on a gigawatt scale campus nearby.
The Trend Is Going International
For the first time, Data Center Watch's quarterly report documented organized opposition campaigns outside the United States, citing activity in Europe, Australia, and South Africa. That matters for enterprises that have started diversifying capacity commitments internationally specifically to de-risk US siting delays; the same water, power, and community impact objections that slowed projects in Georgia, Virginia, and Texas are now showing up wherever hyperscalers try to build at similar scale. European regulators in particular have been quicker than their US counterparts to attach mandatory environmental impact assessments to large data center applications, which suggests the international timeline for these fights may move even faster than the US version did.
The practical implication is that geographic diversification alone will not solve the siting problem. A capacity strategy built on the assumption that some region, somewhere, will always be fast and uncontested is starting to look optimistic. The constraint is becoming close to universal, which means the real differentiator between vendors will be how well they have built local relationships and staged permitting, not which country they picked. Providers that treat community engagement as a core competency, on par with power procurement or chip supply, are the ones likely to keep delivering on schedule while competitors get stuck in county commission hearings.
Regulation Is Moving Almost as Fast as the Backlash
Thirty state legislatures have introduced or adopted data center specific rules so far this year, covering everything from mandatory water disclosure to new tax incentive conditions to grid cost allocation. That is a faster pace of regulatory change than most enterprise sourcing teams are built to track, and it means the permitting environment a vendor described during contract negotiation six months ago may no longer describe the environment the project actually has to clear today. Some of these bills started as narrow water reporting requirements and were amended mid session into much broader environmental review mandates, which is exactly the kind of scope creep that catches capacity planners off guard.
This is the direct link to what Texas just did. Governor Abbott's TCEQ freeze did not happen in a vacuum; it happened inside a year where states have been actively rewriting the rulebook for data center approval in real time, often in response to exactly the kind of community pressure Data Center Watch is now quantifying at scale. A sourcing team that reads Texas as an isolated political event, rather than as one data point inside this larger regulatory shift, is missing the pattern that actually determines how the next twelve months of permitting will go.
Reading This Alongside Texas
This report and the Texas moratorium are two views of the same underlying shift. Data Center Watch measures the problem in dollars and project counts; Texas shows what the problem looks like once a state government decides to act on it directly rather than let county commissions fight it out case by case. Expect more states to follow Texas's lead in converting diffuse local opposition into a single, sweeping regulatory action, because a governor's office can move faster and with more leverage than dozens of separate county boards ever could, once the political cost of inaction outweighs the political cost of upsetting developers.
The combined picture argues for a change in how enterprises underwrite data center capacity commitments. Siting and permitting deserve an ongoing risk line in the vendor scorecard, refreshed every quarter alongside the kind of data Data Center Watch now publishes, starting the moment a developer shows land control and a power letter of intent. The buildout keeps accelerating in dollar terms, and every quarter of continued acceleration makes the assumption that a given project will sail through untouched a costlier one to hold onto.
The Takeaway for Buyers
When negotiating multi year capacity commitments, ask providers for the physical location of a facility and also for the rate of organized opposition among comparable projects in that state or country over the last two quarters. That number is now trackable through public reporting, and it is a more honest predictor of your go live date than a developer's groundbreaking press release. Treat it the way you would treat a vendor's on-time delivery record on any other piece of critical infrastructure, because siting delay has become exactly that kind of measurable, recurring risk rather than an occasional bad-luck event.
Build contract language and internal timelines that assume some slippage from local opposition as a normal cost of doing business in this market. The providers worth betting on long term are the ones that treat community engagement and water and power disclosure as core infrastructure work, built into the project plan from day one. Ask for evidence of proactive water usage disclosure and community outreach before signing, because the data now shows regulators and residents are paying very close attention, and a provider with a poor track record in one state tends to hit the same friction in the next one.