A transformation declared done, then a handover
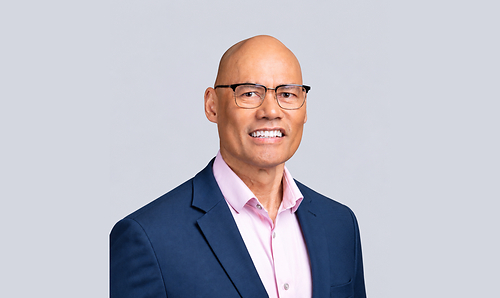
Mike Maddison has stepped down as CEO of NCC Group with immediate effect, closing out a tenure of about four and a half years during which the Manchester-headquartered cybersecurity firm executed what chair Chris Stone called a planned transformation. The exit landed on the same morning NCC issued a trading update for the year ended September 30, 2026, a sequencing that reads less like a surprise departure and more like a leadership change timed to a specific operational milestone. Stone's own language, that Maddison is stepping down after delivering the transformation, frames this explicitly as mission accomplished rather than mission interrupted.
That transformation included the May 2026 divestment of NCC's Escode business, a move that let the company describe itself afterward as a pure-play cybersecurity business rather than a diversified group with a legacy software escrow line attached. Maddison's own exit comment, that he leaves knowing the business is in capable hands, reinforces the framing that this is a planned handoff rather than a board-driven removal, a distinction that matters for how investors read the trading update landing alongside it.
Promoting the CFO into the top seat
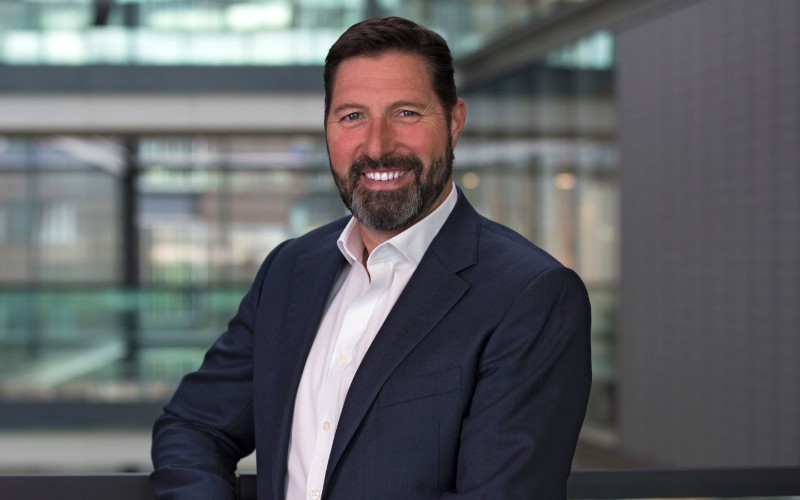
NCC's board moved CFO Guy Ellis directly into the CEO role rather than running an external search, a choice that puts someone already fluent in the company's financial position and recent divestment work in charge going forward. Ellis joined NCC's board as CFO in June 2023 and is credited specifically with strengthening financial performance and delivering the Escode divestment, meaning he was already the executive closest to the transformation Maddison is credited with completing. Promoting from inside removes the ramp-up period an external CEO hire would need to understand a business that just changed its own strategic shape.
Andy Beaver, currently group financial director, steps up as interim CFO to fill the resulting gap, a sequencing that keeps financial continuity intact even as the CEO seat changes hands. This kind of internal cascade, CFO to CEO and financial director to interim CFO, is a lower-disruption path than bringing in outside leadership at both levels simultaneously, particularly for a company reporting results the same week. It trades some fresh external perspective for continuity at a moment the board apparently decided continuity mattered more.
The numbers behind the timing
NCC's trading update reported cyber revenue of 235 million pounds for the year to September 30, 2026, up 3.7 percent from 227.4 million pounds in the prior year, alongside adjusted cyber EBITDA of 16.3 million pounds, roughly 6.9 percent of revenue. Those are modest numbers, consistent with a company that just finished stripping out a non-core business line and is still normalizing its reported base around the remaining pure-play cyber operation. Net cash of 53 million pounds and a share buyback 35 percent executed add up to a balance sheet in reasonable shape to support a leadership transition without external financing pressure.
Pairing a modest but positive growth number with a leadership change is a deliberate signal to the market: the board is saying the strategic pivot worked well enough to hand the business to the person most responsible for its financial execution, rather than waiting for a cleaner set of headline numbers to make that case more dramatically. Ellis's own comment, that the need for trusted independent cyber expertise has never been greater, positions the new leadership around continued demand rather than around fixing anything broken, a framing the board clearly wants investors to accept at face value.
What this says about cybersecurity leadership markets
NCC's internal promotion stands in contrast to how many cybersecurity firms have handled CEO transitions this year, often reaching outside for operators with broader platform or hyperscaler experience to run the next growth phase. NCC instead bet on the executive who already delivered its hardest recent decision, divesting a legacy business line, treating that specific experience as more valuable than an external candidate's broader market credibility. For a mid-cap, UK-listed pure-play cyber firm competing against much larger platform vendors, that choice prioritizes execution continuity over a splashier hire that might have moved the stock more on announcement day.
For CISOs and security leaders evaluating NCC as a vendor or partner, a CEO transition timed precisely to the completion of a strategic pivot is generally a lower-risk signal than one that arrives mid-transformation or alongside a profit warning. The audited FY26 results due December 10, 2026 will be the first real test of whether Ellis's financial discipline translates into operating leadership, since trading updates flatter less than full annual reporting does.
The practical read for buyers and partners
Enterprise security leaders who rely on NCC Group for assessment, assurance, or incident response work should treat this transition as low-disruption rather than a reason to re-evaluate the relationship, given the internal promotion and the absence of any accompanying restructuring of the services teams clients actually work with. The transaction-services agreement covering the Escode divestment running until May 2027 also suggests the company is managing its remaining legacy obligations methodically rather than rushing to close them out under new leadership pressure.
The more durable lesson for other mid-cap technology and security firms is that completing a stated strategic transformation, then handing leadership to the executive who delivered the hardest part of it internally, is a credible way to signal stability to customers and investors simultaneously. NCC's board chose continuity of execution over the market attention a splashier external CEO hire might generate, a trade-off that will be judged fairly by whether cyber revenue growth accelerates past the 3.7 percent reported this cycle under Ellis's first full year in charge.