The math behind the buildout
Arete Research puts a hard number on a trend most technology leaders have only felt anecdotally through vendor pricing. The firm estimates that Alphabet, Amazon, Meta and Microsoft together will spend about 1.8 trillion dollars on capital expenditure through 2028, against roughly 1.2 trillion dollars of expected underlying operating cash flow over the same period, a gap of about 600 billion dollars. J.P. Morgan Asset Management puts expected 2026 operating cash flow for the group at about 575 billion dollars.
The share of that cash flow absorbed by capex is what has shifted so quickly. J.P. Morgan estimates capital spending consumed about 60 percent of operating cash flow in 2025 and is on track to hit 90 to 100 percent in 2026. The same five largest American hyperscalers are now expected to spend 697 billion dollars this year alone, up 173 billion dollars since the start of the year, even as the group held roughly 430 billion dollars in cash and marketable securities as of the first quarter.
What Arete's Jim Fontanelli actually worries about
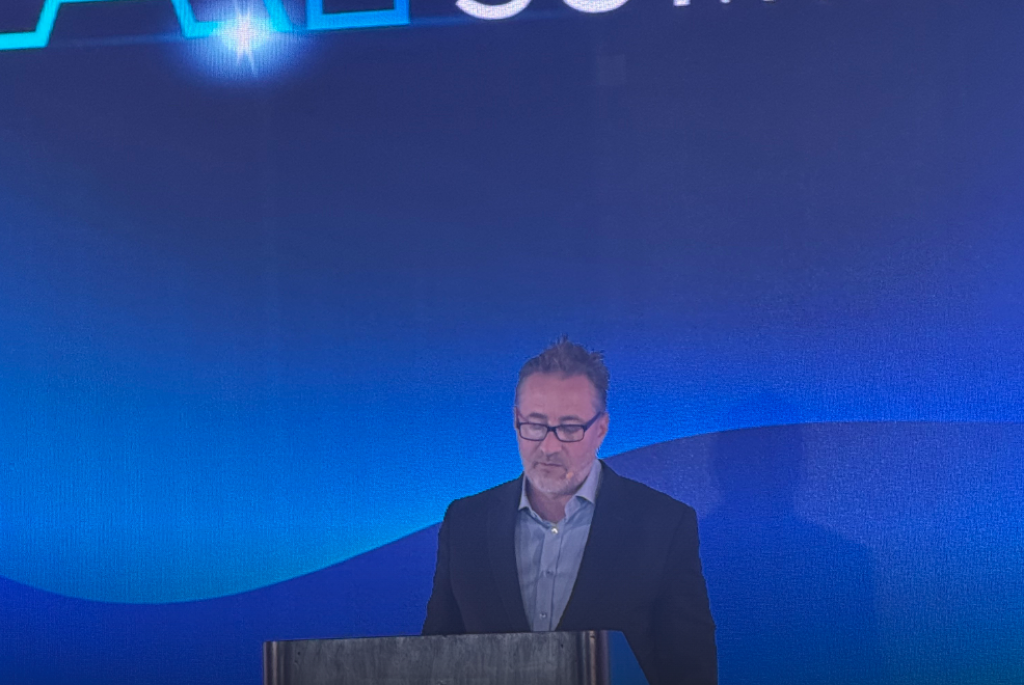
Jim Fontanelli, Arete's founding partner, is careful to separate the headline gap from an actual liquidity crisis. "The 600 billion dollar difference is not exactly a funding shortfall," he said, since these companies can and do borrow, issue equity, or draw down reserves. His concern is narrower and more structural: "When capital spending takes nearly every dollar the business generates, the cushion thins," leaving less room for acquisitions, buybacks, or a shock absorber if AI revenue arrives more slowly than planned.
Fontanelli's real worry is overbuilding rather than underfunding. Even unused data center capacity still carries depreciation, financing costs, and operating expense, so the risk shows up on the income statement long before it shows up as an empty building. He watches token prices as his preferred real time demand signal, and says they have been flat or rising since January, which he reads as evidence that demand has not yet cracked.
The neocloud layer has no cushion at all
If hyperscalers have thinning margins of safety, specialized AI cloud providers have almost none. Nscale, a British AI cloud operator, reported 140.6 million dollars in revenue for the first half of 2026 against a 1.02 billion dollar net loss, financed in part through 3.1 billion dollars in convertible bonds, including 1 billion dollars from Nvidia itself. A single customer accounted for 52 percent of that half year's revenue, a level of concentration that would be unremarkable for an early stage startup but is a genuine red flag for a company building and financing physical infrastructure at this scale.
That concentration is the structural problem. Specialized AI clouds lack the advertising, ecommerce, or enterprise software cash flows that let Alphabet, Amazon, Meta and Microsoft absorb a slow quarter without touching their financing. Compounding that, neither OpenAI nor Anthropic, the customers underwriting much of this new capacity, currently holds an investment grade credit rating, which means a meaningful share of the collateral behind this buildout is a promise rather than a balance sheet, and that promise is what a growing share of new data center debt is actually priced against rather than any hard asset a lender could repossess and resell.
Stargate shows how the financing actually works
The OpenAI backed Stargate project illustrates how debt, not just equity, is now funding AI infrastructure directly. J.P. Morgan originated 9.6 billion dollars across two construction loans for the Abilene, Texas campus alone, a structure that would have been unusual for a data center project financed primarily on the strength of a single tenant's growth projections just a few years ago. Combined annualized revenue at OpenAI and Anthropic is expected to pass 25 billion dollars by the end of 2026, the figure lenders are implicitly counting on to service that debt over its full term.
Current estimates put the payback period on newly deployed computing capacity at one to two years, a timeline that assumes sustained demand growth rather than a plateau. That assumption is now shared by banks writing construction loans as much as by the hyperscalers themselves, which means a slowdown in AI lab revenue would ripple through credit markets directly, not just through next quarter's capex guidance on an earnings call, and would do so faster than most enterprise buyers currently appreciate.
The signal CIOs should actually watch
The fact that more than 70 percent of data center capacity under construction today is already pre-leased is genuinely reassuring: this is not speculative building running ahead of demand. What it does not resolve is where the financial risk sits if demand growth merely slows rather than stops. That risk is concentrated in the balance sheets of neoclouds and AI labs, even while the hyperscalers that dominate headlines remain comfortably capitalized and able to absorb a slower quarter without touching their credit lines.
The practical implication for any enterprise evaluating a GPU cloud or specialized AI infrastructure vendor is to look past price per GPU hour and examine customer concentration and the credit quality of whoever is backing that vendor's financing. A provider with one customer generating half its revenue, financed through convertible debt, carries a different risk profile than a hyperscaler running the same workload, even at a similar headline price per hour of compute.
What changes if the gap does not close
If AI demand growth slows from here rather than accelerating, hyperscalers have the diversified cash flow to absorb a longer payback period without much disruption to the services enterprises already depend on. Neoclouds and thinly capitalized AI labs do not have that same room, and Fontanelli's preferred early warning signal, token pricing, is the metric worth tracking over the next few quarters rather than quarterly capex headlines alone, since pricing tends to move before contracts get renegotiated.
For technology leaders building multi year AI infrastructure plans, this argues for spreading GPU cloud commitments across providers with genuinely different financing structures rather than consolidating with whichever vendor offers the lowest price today. Treat a counterpart's balance sheet, not just its roadmap, as part of the vendor risk assessment before signing anything measured in years rather than months, and revisit that assessment at every renewal rather than only at signing.