A pandemic-era acquisition gets unwound
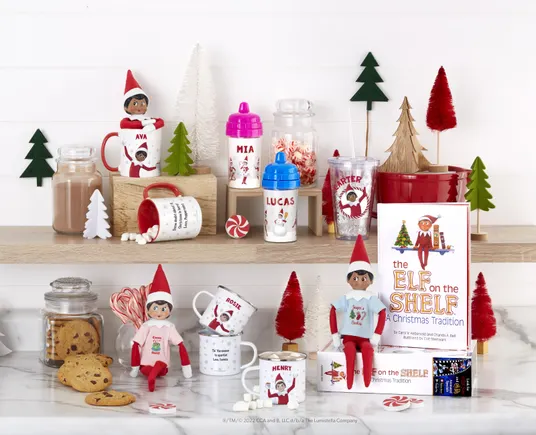
1-800-Flowers announced it is selling PersonalizationMall.com and Things Remembered to PlanetArt for 45 million dollars in cash. The company paid 245 million dollars for PersonalizationMall.com alone back in 2020, at the height of pandemic-driven ecommerce enthusiasm when personalized gifting looked like a durable growth category worth a premium multiple. Six years later, the asset changed hands for roughly 18 percent of what 1-800-Flowers originally paid for it, a gap large enough that it is not explained by normal depreciation or amortization alone.
CEO Adolfo Villagomez described the sale as a way to sharpen the company's portfolio focus, strengthen its financial position, and create capacity to invest in the initiatives it believes offer the greatest opportunity. That is standard divestiture language, and it is also honest about what is happening: a company built around its core flowers and gifting brands is walking away from a personalization-focused acquisition that did not deliver the scale or margin that justified its original price.
What a 200 million dollar gap actually signals
A loss of this size rarely comes from one bad quarter. It typically reflects a slower, compounding mismatch between an acquisition's expected synergies and its actual integration reality. Personalized gifting ecommerce is operationally harder than generic ecommerce: custom products mean more SKUs, more production complexity, longer fulfillment windows, and less inventory flexibility when demand shifts. Those are exactly the kinds of operational frictions that erode margin slowly enough that a board keeps funding the business for years before a clean-break sale becomes the obviously correct move.
For technology and operations leaders evaluating a similar acquisition today, the lesson is not that personalization ecommerce is a bad category. It is that the technology and fulfillment infrastructure required to run it profitably at scale needs to be underwritten as carefully as the brand and customer acquisition story, because the brand premium that justified a 245 million dollar price tag in 2020 clearly did not translate into an operating model worth anywhere near that six years later.
PlanetArt is buying at a very different price point
PlanetArt's 45 million dollar purchase price gives it PersonalizationMall.com and Things Remembered without the integration debt or growth expectations that came with 1-800-Flowers' original 2020 deal. Buying distressed or discounted digital assets after a prior owner has already absorbed the hard lessons of running them is a recognizable pattern in ecommerce consolidation right now, and it is often a more disciplined way to acquire customer bases and brand equity than paying a growth-era premium for the same assets.
The commercial partnership structure, where 1-800-Flowers continues offering select PersonalizationMall products to its own customers even after the sale, is a sensible way to preserve some cross-sell value without carrying the operational cost of owning the brand outright. It is a model worth watching: a seller retains a thin revenue-sharing relationship with the asset it just divested, capturing some of the upside without the balance sheet exposure, while the buyer gets full operational control at a fraction of the original price.
The specialty ecommerce category is quietly consolidating
This deal is not an isolated event. Specialty and personalization-focused ecommerce brands acquired during the 2020 and 2021 growth window are increasingly showing up as divestitures or write-downs as their original owners reassess which acquisitions actually pay for themselves. The economics that made niche, personalization-heavy ecommerce attractive during a period of elevated demand and cheap capital look considerably less attractive now that growth has normalized and the operational complexity of running custom fulfillment at scale has to be funded out of current cash flow rather than growth-stage capital.
For PE-backed retail technology operators, this pattern is worth tracking as a category-level signal, not just a single company's story. If a well-resourced public company with 1-800-Flowers' logistics experience could not make this asset work at its original price, that is a useful benchmark for any PE firm currently evaluating a similar acquisition target, and it argues for underwriting integration cost and fulfillment complexity more conservatively than the 2020 vintage of deals generally did.
What this means for build versus buy decisions
For a technology leader weighing whether to build a personalization capability in-house versus acquiring one, this deal is a useful data point in favor of building narrowly rather than buying broadly. 1-800-Flowers acquired an entire standalone personalization ecommerce business, with its own brand, customer base, and fulfillment operation, rather than licensing or building a personalization engine that could plug into its existing gifting infrastructure. That decision added complexity the company ultimately could not justify keeping.
A narrower approach, building or licensing the specific personalization capability and applying it to an existing customer base and fulfillment network, carries less integration risk than acquiring a parallel business with its own operational stack. It is a less exciting announcement than a 245 million dollar acquisition, but based on this outcome, it is the approach more likely to still look like a good decision six years later, and it is the version a CFO can actually defend in a board meeting without a write-down attached to it.
The timing question every acquirer should ask now
The gap between 2020's acquisition climate and today's is itself worth naming explicitly. Capital was cheap in 2020, growth multiples were generous, and a personalization-focused ecommerce brand with pandemic-era tailwinds looked like a reasonable bet at a premium price. None of those conditions hold today, and deals priced under those earlier assumptions are the ones most likely to surface as write-downs or forced divestitures over the next several quarters as their original underwriting gets tested against current reality.
Any technology or operations leader sitting on a similar vintage acquisition should treat this deal as a prompt to re-run the integration math now, honestly, rather than waiting for a board to force the question. 1-800-Flowers waited six years to make this call. The companies that get ahead of a similar reassessment, rather than carrying an underperforming asset until the gap becomes undeniable, generally preserve more of the original deal value and more credibility with the capital markets watching how they manage it.